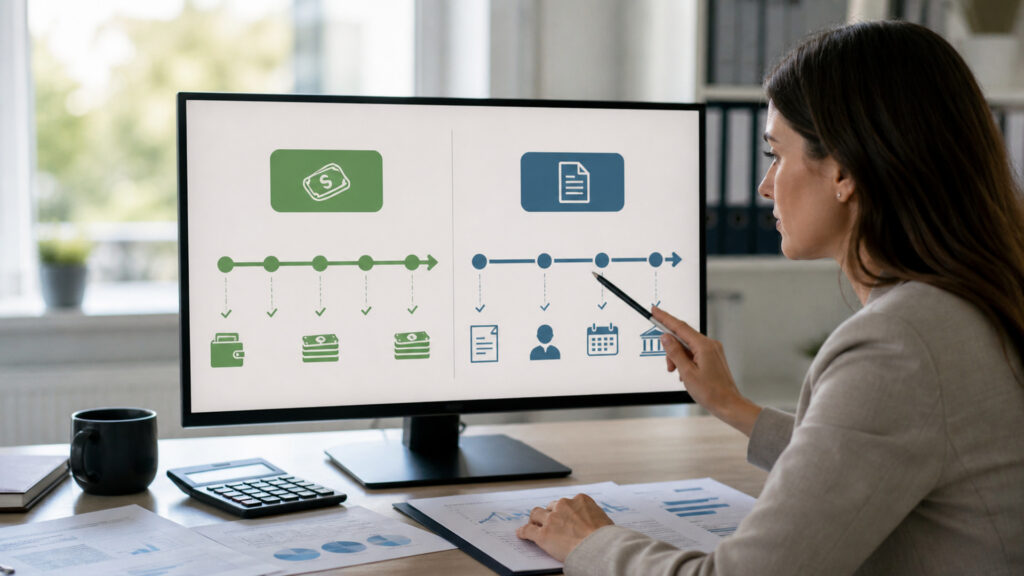
Cash basis and accrual accounting differ mainly in the event that causes revenue or expense to enter a reporting period. Cash basis generally uses receipt or payment as the trigger. Accrual accounting separates economic activity from settlement, recognizing revenue when earned and expenses when incurred under the applicable framework.
That timing difference creates different records. An accrual ledger can show customer receivables before collection, supplier payables before payment, prepaid assets before consumption, and liabilities before cash leaves. A cash-basis view may postpone those effects until settlement. The methods can therefore report different profit for the same month even though lifetime cash and economics eventually converge. Eligibility and tax treatment require jurisdiction-specific review.