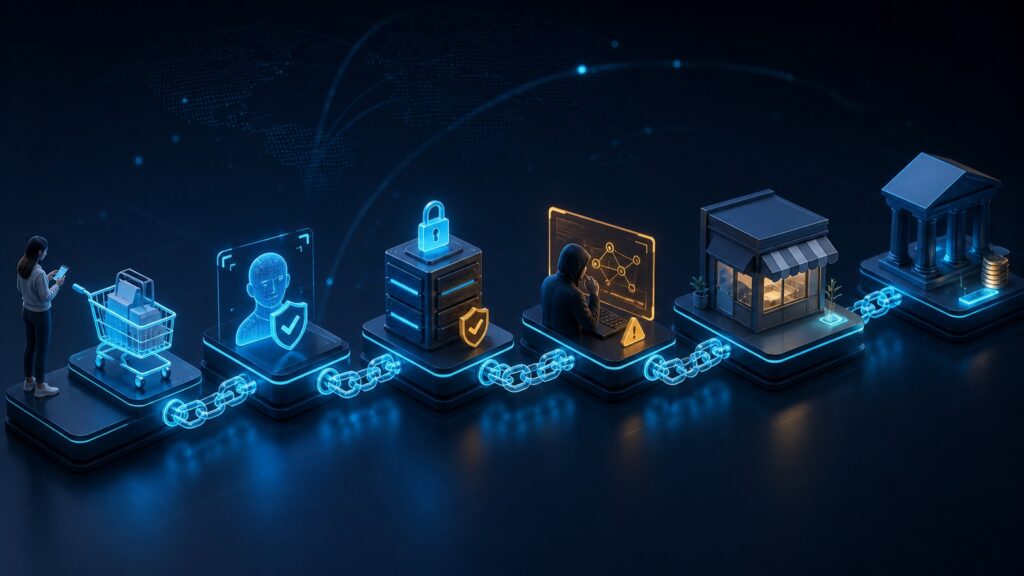
A digital payment platform does more than return a success or failure message. Its results tell a business whether to release an order, wait for confirmation, ask the customer to authenticate, investigate uncertainty, or process an authorized remedy. Those actions need a clear sequence because payment, fulfillment, and financial records do not always update together.
The platform's role in that sequence matters most when something goes wrong. A timeout is not necessarily a decline, a payment approved for capture is not a bank deposit, and a refund request is not proof that money has been returned. Acting on the precise state keeps an ordinary exception from becoming a duplicate charge or an unfulfilled paid order.