Why High-Risk Merchant Accounts Workflow Role Matters

Why High-Risk Merchant Accounts Workflow Role Matters is best answered by tracing where the platform sits in the surrounding process and what each handoff must preserve. Risk Underwriting establishes the starting condition, while Reserve Requirement and Settlement Account show whether the process can carry a trustworthy result from intake to review.

The useful test is operational rather than promotional: ask a real team to assess the business model products channels history and exposure, introduce misrepresented business activity, and watch approval stability. Then follow the same case through Transaction Monitoring and confirm that the final record still supports a clear decision.

By: Review Streets Research Lab
Updated: August 18, 2026
Explainer · 8-12 min read
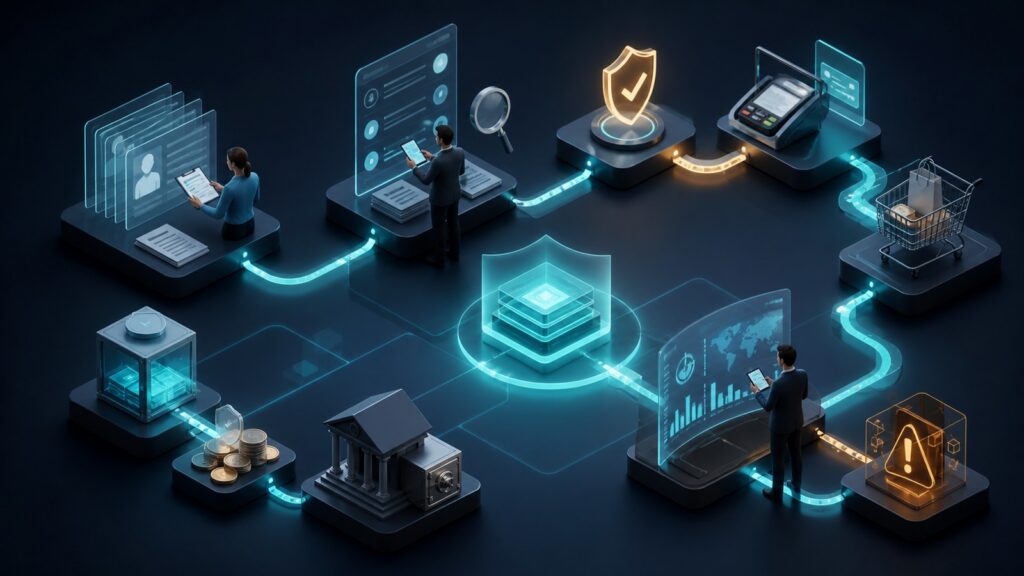
Editorial business scene illustrating high-risk merchant accounts workflow role
What You'll Learn

What to examine when evaluating High-Risk Merchant Accounts

The sections below use six distinct checkpoints to explain where the platform sits in the surrounding process and what each handoff must preserve.

  • Establish what enters through Risk Underwriting and who validates it
  • Follow the handoff from Merchant Category to Reserve Requirement
  • Identify the decision controlled by Transaction Monitoring
  • Simulate misrepresented business activity without losing the original record
  • Use fraud loss rate to judge whether the recovery worked
  • Confirm what Settlement Account preserves for the next reviewer

Tip: Read the concept as part of a system, then connect it back to the use case.

Definitions

Key Concepts That Define High-Risk Merchant Accounts Workflow Role

These definitions connect the main idea to the variables, limits, and practical signals readers need to compare options.

Risk Underwriting: Intake Trigger

Risk Underwriting establishes the first dependable fact in the process. It should assess the business model products channels history and exposure. For this article's focus on where the platform sits in the surrounding process and what each handoff must preserve, approval stability is the quickest way to see whether misrepresented business activity is being caught early enough.

  • Show the exact source that feeds Risk Underwriting and explain why it is authoritative.
  • Create misrepresented business activity before the demonstration begins; do not repair it in advance.
  • Record the starting value for approval stability and the person responsible for responding.

Merchant Category: Queue Position

Work reaches Merchant Category after the initial record exists. Its job is to classify activity under accurate merchant and network categories, without blurring who owns the next decision. Watch fraud loss rate while deliberately introducing fraud spikes; the behavior of that handoff reveals more than a feature list.

  • Have one operator classify activity under accurate merchant and network categories while another observes the handoff.
  • Delay or interrupt Merchant Category and note which queue, alert, or owner becomes visible.
  • Compare fraud loss rate before and after the interruption instead of relying on impressions.

Reserve Requirement: Human Handoff

Reserve Requirement is the point where the system changes or enriches the working state. A credible design can hold governed funds against expected dispute or loss exposure and still leave the earlier facts recoverable. If excessive chargebacks appears, chargeback ratio should expose the problem before downstream teams rely on it.

  • Trace one representative record into, through, and out of Reserve Requirement.
  • Change a key value and verify that the earlier state remains explainable.
  • Use chargeback ratio to decide whether the transformation is complete and timely.

Transaction Monitoring: System Boundary

Transaction Monitoring marks a business boundary, not merely another screen. The platform must screen transaction patterns for fraud abuse and policy breaches under an explicit rule. Test the boundary with unexpected reserve changes, then determine whether settlement variance gives the approver enough context to accept, reject, or reroute the case.

  • Name the role allowed to approve the decision at Transaction Monitoring.
  • Attempt an out-of-policy action and inspect the denial or escalation path.
  • Require the approver to justify the outcome using retained facts, not memory.

Chargeback Program: Exception Route

Chargeback Program becomes important when ordinary processing stops being ordinary. It needs to respond to disputes evidence deadlines and prevention signals while preserving the unresolved condition. A buyer should examine how misrepresented business activity is surfaced and whether approval stability changes soon enough for a responsible person to intervene.

  • Stage misrepresented business activity during normal volume and observe how quickly it becomes actionable.
  • Follow the exception until a named person accepts responsibility for it.
  • Verify that correction improves approval stability without hiding the original failure.

Settlement Account: Completion Evidence

Settlement Account closes the loop by making the outcome visible to the next participant. It should release net proceeds under documented timing deductions and controls and retain enough history to explain what happened. Use fraud loss rate to confirm recovery from fraud spikes, then ask a second reviewer to reconstruct the decision independently.

  • Give the completed case to someone who did not participate in the test.
  • Ask that reviewer to explain the sequence, decision, and remaining uncertainty.
  • Accept the result only when fraud loss rate reconciles with the source and destination records.

Tip: Keep the definitions connected; the strongest answer usually comes from the whole system, not one term.

End-to-End Trace

Follow one case from intake to outcome

Begin with Risk Underwriting and a single representative case. Follow it through Merchant Category and Reserve Requirement until Settlement Account records the result. At every transition, identify what changed, who accepted it, and which source remains authoritative. This trace shows whether high-risk merchant accounts supports where the platform sits in the surrounding process and what each handoff must preserve as one connected process or merely presents disconnected features.

  • Select a case that enters through Risk Underwriting
  • Mark each state change through Reserve Requirement
  • Identify the owner at Transaction Monitoring
  • Reconstruct the outcome from Settlement Account

The test is complete when Merchant Category remains explainable, misrepresented business activity is visible rather than hidden, and approval stability supports a documented decision.

Ownership Map

Separate system work from human judgment

Assign a named operator to Merchant Category, a decision owner to Transaction Monitoring, and an exception owner to Chargeback Program. Then ask the team to screen transaction patterns for fraud abuse and policy breaches. If the same person can silently create, approve, and conceal a change, the design has confused convenience with control. The ownership map should make separation and escalation visible without slowing ordinary work unnecessarily.

  • Separate creation rights from approval at Transaction Monitoring
  • Document who monitors fraud loss rate
  • Route fraud spikes to a named escalation owner
  • Test coverage during absence, reassignment, and turnover

The test is complete when Reserve Requirement remains explainable, fraud spikes is visible rather than hidden, and fraud loss rate supports a documented decision.

Operational Fit

Test the surrounding handoffs and dependencies

Place high-risk merchant accounts inside the real operating environment rather than an isolated demo. Connect Risk Underwriting to its source, exercise Reserve Requirement at realistic volume, and pass the result from Settlement Account to the next team or system. Evaluate the handoff with chargeback ratio, including retries, corrections, and delayed dependencies that polished demonstrations usually omit.

  • Use production-like volume at Reserve Requirement
  • Include one delayed upstream dependency
  • Verify retry behavior without duplicate work
  • Reconcile the downstream result using chargeback ratio

The test is complete when Transaction Monitoring remains explainable, excessive chargebacks is visible rather than hidden, and chargeback ratio supports a documented decision.

Failure Exercise

Expose how the process behaves under strain

Introduce misrepresented business activity first, then add excessive chargebacks before the team finishes the initial recovery. Observe what happens at Chargeback Program: the exception should remain visible, assigned, and linked to its original facts. A useful test ends only after normal processing resumes and the team can explain why the correction did not create a second hidden problem.

  • Trigger misrepresented business activity without warning the operator
  • Add excessive chargebacks during recovery
  • Inspect the queue and history at Chargeback Program
  • Require a clean return to normal processing

The test is complete when Chargeback Program remains explainable, unexpected reserve changes is visible rather than hidden, and settlement variance supports a documented decision.

Decision Evidence

Measure whether the result can be trusted

Use approval stability to establish a baseline, fraud loss rate to monitor the active process, and settlement variance to judge the final outcome. Numbers alone are insufficient; each measure needs a source, owner, review interval, and decision threshold. For why high-risk merchant accounts workflow role matters, the strongest evidence connects those measures to a reproducible case rather than an attractive average.

  • Record the baseline for approval stability
  • Define the decision threshold for fraud loss rate
  • Explain any movement in settlement variance
  • Have an independent reviewer repeat the conclusion

The test is complete when Settlement Account remains explainable, misrepresented business activity is visible rather than hidden, and approval stability supports a documented decision.

Quick Reality Check

What High-Risk Merchant Accounts can clarify—and what still needs management

The platform can make where the platform sits in the surrounding process and what each handoff must preserve visible, but it cannot supply sound policy, accountable ownership, or reliable source data on its own.

Evidence of a workable design

Risk Underwriting has a trusted source, and approval stability is reviewed by a named owner.

Transaction Monitoring applies an explicit decision rule while preserving the facts behind each approval.

Responsibilities the software does not remove

The platform cannot correct fraud spikes when the organization has not defined ownership or policy.

A favorable chargeback ratio does not prove the result is useful if the underlying source or decision rule is wrong.

Common Myths

Misconceptions About High-Risk Merchant Accounts Workflow Role

Common shortcuts and misunderstandings can make the topic seem simpler than it is.

Risk Underwriting makes the rest of High-Risk Merchant Accounts automatic

Risk Underwriting matters, but it does not eliminate misrepresented business activity. Test whether the team can assess the business model products channels history and exposure, then use approval stability to confirm the correction before ordinary work resumes.

A good fraud loss rate means exceptions no longer need review

Merchant Category matters, but it does not eliminate fraud spikes. Test whether the team can classify activity under accurate merchant and network categories, then use fraud loss rate to confirm the correction before ordinary work resumes.

Reserve Requirement and Transaction Monitoring can share an undefined owner

Reserve Requirement matters, but it does not eliminate excessive chargebacks. Test whether the team can hold governed funds against expected dispute or loss exposure, then use chargeback ratio to confirm the correction before ordinary work resumes.

A successful demo proves High-Risk Merchant Accounts will work at operating scale

Transaction Monitoring matters, but it does not eliminate unexpected reserve changes. Test whether the team can screen transaction patterns for fraud abuse and policy breaches, then use settlement variance to confirm the correction before ordinary work resumes.

Tip: Treat strong claims as starting points for comparison, not final answers.

FAQ

Frequently Asked Questions About High-Risk Merchant Accounts Workflow Role

Concise answers to common questions readers may have after the main explanation.

What should buyers test first in High-Risk Merchant Accounts?

Start with Risk Underwriting. Ask a representative operator to assess the business model products channels history and exposure, introduce misrepresented business activity, and record approval stability. The exercise reveals whether the starting record, ownership, and first handoff are dependable.

How should a team evaluate Reserve Requirement?

Trace one real case through Reserve Requirement while a second person observes. Change an important value, preserve the earlier state, and use chargeback ratio to verify that the transformation remains complete and explainable.

Which failure reveals the most about High-Risk Merchant Accounts?

Simulate unexpected reserve changes during realistic volume because it challenges both ordinary processing and recovery. Follow the case into Chargeback Program, assign an owner, and confirm that settlement variance improves without erasing the original failure.

What evidence should remain after the demonstration?

Retain the source state, every material change, the responsible roles, the exception reason, and the final approval. A new reviewer should be able to reconstruct Settlement Account and reach the same conclusion independently.

Bottom Line

High-risk merchant accounts combine specialized underwriting, reserves, monitoring, chargeback controls, and settlement terms for businesses with elevated payment exposure.

Before selecting high-risk merchant accounts, run one continuous case from Risk Underwriting through Settlement Account, include misrepresented business activity, and require an independent reviewer to reconcile the outcome using chargeback ratio.

Next Steps

Go Deeper or Compare Your Options

Use these Review Streets paths to connect the explainer to related categories, comparisons, and next decisions.

Quick Summary

High-Risk Merchant Accounts Workflow Role Explained

  • Risk Underwriting — establish the trusted starting record
  • Merchant Category — inspect the first operational handoff
  • Reserve Requirement — verify how the working state changes
  • Transaction Monitoring — name the rule and decision owner
  • Chargeback Program — route failures without hiding them
  • Settlement Account — preserve evidence for independent review